Understanding the Credit Score for a Mortgage in New Jersey
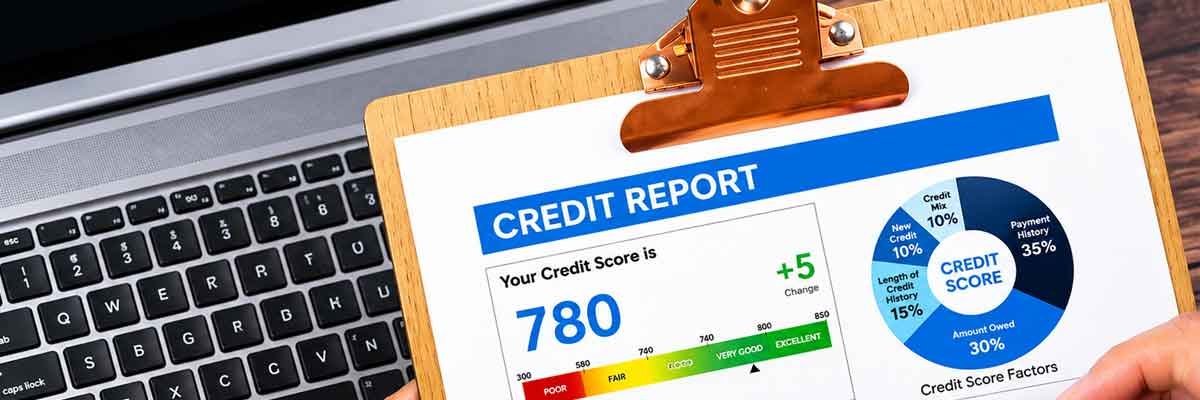
A credit score is a numerical representation of your credit history and repayment behavior. Mortgage lenders use it, along with your credit report and other financial information, to evaluate the risk of lending you money.
Most traditional credit scores range from 300 to 850. Generally, a higher score indicates a stronger history of managing borrowed money and making payments on time.
However, your credit score is not the only factor considered during mortgage underwriting.
Lenders may also review:
- ✓ Payment history and outstanding debts.
- ✓ Credit card balances and utilization.
- ✓ Length of credit history.
- ✓ Recent credit inquiries and new accounts.
- ✓ Debt-to-income (DTI) ratio.
- ✓ Employment and income stability.
- ✓ Available savings and financial reserves.
- ✓ Down payment and property value.
For example, a borrower with a 680 credit score, stable employment, manageable debt and sufficient savings may present a stronger overall application than someone with a higher score but substantial outstanding obligations.
What Credit Score Do You Need to Buy a House in NJ?
The minimum credit score depends on the mortgage program, underwriting method and lender requirements.
Here is a general comparison of commonly used mortgage programs.
| Mortgage Program | Credit Score Guidance | Important Considerations |
|---|---|---|
| FHA | 580 for maximum financing; 500 to 579 requires maximum 90% LTV | Lenders may impose higher minimums. |
| Conventional | 620 for manually underwritten fixed-rate loans under applicable Fannie Mae requirements | Automated underwriting evaluates broader risk factors. |
| Conventional ARM | 640 for manually underwritten loans under applicable Fannie Mae requirements | Automated underwriting follows separate risk assessment. |
| VA | No minimum score established by VA | Individual lenders set their own standards. |
| USDA | No single universal score requirement applicable to every underwriting outcome | GUS findings and lender overlays matter. |
| Jumbo | Lender-specific | Higher scores and stronger financial profiles may be expected. |
These figures are program-specific guidance, not guaranteed approval thresholds. Other eligibility requirements, lender overlays and underwriting findings apply.
For New Jersey borrowers, NJHMFA's First-Time Homebuyer Program has a separate minimum representative credit score of 620. Additional DTI restrictions apply to borrowers with scores below 660.
Understanding these distinctions is essential when comparing mortgage options.
Credit Score Requirements for Different Mortgage Loan Types
1. FHA Loans: Flexible Credit Requirements for Eligible Buyers
FHA loans are insured by the Federal Housing Administration and are designed to make homeownership accessible to eligible borrowers.
They can be particularly useful for first-time buyers and borrowers who have limited savings or a less established credit profile.
According to HUD's FHA Handbook 4000.1:
- ✓ Borrowers with a minimum decision credit score of 580 may qualify for maximum financing, subject to other requirements.
- ✓ Borrowers with scores between 500 and 579 are limited to a maximum loan-to-value ratio of 90%.
- ✓ Borrowers with scores below 500 are not eligible for standard FHA-insured financing.
For a typical eligible purchase, the 580 threshold corresponds to the potential for a 3.5% minimum down payment. Borrowers in the 500 to 579 range generally need at least 10% down.
However, lenders may establish higher minimum credit score requirements.
Why Consider an FHA Loan?
- ✓ Lower down payment requirements for eligible borrowers.
- ✓ Flexible underwriting options.
- ✓ Potentially suitable for borrowers with limited credit history.
- ✓ Available for qualifying primary residences.
FHA loans also include mortgage insurance requirements that borrowers should consider when comparing total borrowing costs.
2. Conventional Loans: Credit Requirements and Qualification
Conventional mortgages are not insured by the federal government. They generally follow guidelines established by Fannie Mae or Freddie Mac, although lenders can apply additional requirements.
Under Fannie Mae's November 2026 Selling Guide:
- ✓ Manually underwritten fixed-rate loans have a 620 minimum credit score requirement under the applicable eligibility framework.
- ✓ Manually underwritten adjustable-rate mortgages have a 640 minimum.
- ✓ Desktop Underwriter (DU) casefiles do not have a fixed minimum third-party credit score requirement for automated risk assessment.
This last point is important. Since November 15, 2025, Fannie Mae's DU system has evaluated creditworthiness through its proprietary risk assessment rather than relying on a fixed minimum third-party score.
Nevertheless, lenders still review credit information and may apply their own minimum score requirements.
Conventional mortgages may offer advantages such as:
- ✓ Flexible down payment options for eligible borrowers.
- ✓ Potentially lower mortgage insurance costs for stronger credit profiles.
- ✓ Different loan terms and property eligibility options.
- ✓ Opportunities to remove private mortgage insurance when applicable requirements are met.
Conventional loans can be worth exploring if you have established credit, manageable debts and sufficient funds for your purchase.
3. Adjustable-Rate Mortgages (ARMs): How Credit Affects Eligibility
An adjustable-rate mortgage begins with an interest rate that may remain fixed for an initial period before adjusting according to the loan's terms.
For example, a 5/1 ARM typically has an initial five-year fixed-rate period, followed by annual adjustments.
Credit requirements depend on the underwriting method and lender.
Under Fannie Mae's current manually underwritten framework, the minimum credit score for an ARM is 640. Automated underwriting follows its own risk assessment, while lenders may apply additional restrictions.
When considering an ARM, borrowers should evaluate:
- ✓ Credit score and overall financial strength.
- ✓ Initial interest rate and fixed-rate period.
- ✓ Adjustment frequency.
- ✓ Interest rate caps.
- ✓ Potential future monthly payments.
- ✓ Ability to manage higher payments if rates increase.
An ARM may be appropriate for certain borrowers, but the initial interest rate should not be the only consideration.
4. Jumbo Loans: Credit Expectations for Higher-Value Properties
Jumbo mortgages are designed for loan amounts exceeding the applicable conforming loan limits.
These loans are particularly relevant in higher-priced New Jersey housing markets, where buyers may need financing beyond standard conforming limits.
Unlike FHA loans, jumbo mortgages do not have one universal government-established minimum credit score.
Lenders establish their own qualification requirements. Depending on the lender, loan amount and borrower profile, they may expect stronger credit, lower DTI ratios, larger down payments and additional financial reserves.
Common underwriting considerations include:
- ✓ Strong credit history.
- ✓ Consistent income and employment.
- ✓ Substantial savings and liquid reserves.
- ✓ Manageable existing debt.
- ✓ Property appraisal and loan-to-value ratio.
A borrower purchasing an expensive property in Bergen, Essex or Morris County may need to explore jumbo financing if the required loan amount exceeds the applicable conforming limit.
A mortgage professional can help determine whether a conventional conforming or jumbo loan is more appropriate.
5. VA and USDA Loans: Additional Options to Consider
Eligible veterans, active-duty service members and certain surviving spouses may qualify for VA-backed mortgages.
The Department of Veterans Affairs does not establish a minimum credit score requirement. However, private lenders evaluate creditworthiness and may apply their own minimum score requirements.
USDA loans are designed for eligible buyers purchasing qualifying properties in designated rural and suburban areas.
USDA underwriting considers the overall borrower profile and automated underwriting findings. Credit requirements can differ depending on whether the application receives an acceptable automated recommendation or requires manual underwriting. Lenders may also apply their own overlays.
These programs demonstrate why borrowers should compare multiple mortgage options instead of assuming they need a particular credit score to purchase a home.
New Jersey Mortgage Credit Requirements and NJHMFA Programs
New Jersey buyers may have access to mortgage programs offered through the New Jersey Housing and Mortgage Finance Agency (NJHMFA).
These programs are designed to support eligible homebuyers through participating lenders and may include down payment assistance options.
However, program eligibility involves more than meeting a credit score threshold.
According to the NJHMFA lender policy guide effective October 19, 2026, its First-Time Homebuyer Program requires:
NJHMFA First-Time Homebuyer Credit Requirements
Other requirements involving income, property eligibility, purchase price and program participation also apply.
NJHMFA offers several programs, and their requirements are not necessarily identical. Buyers should verify the current rules for the specific program they intend to use.
A borrower with a 640 credit score may meet the program's minimum score requirement but still need to satisfy the additional DTI restriction.
This is why evaluating your complete financial profile before applying is important.
How Credit Scores Affect Mortgage Interest Rates and Monthly Payments
Your credit score can influence the interest rate and pricing offered by a lender.
Generally, borrowers with stronger credit profiles may qualify for more competitive mortgage pricing, while borrowers with weaker credit profiles may face higher borrowing costs or fewer available options.
Consider the following hypothetical example.
Illustrative Mortgage Payment Comparison
Assume two borrowers purchase a $400,000 home with a $320,000 mortgage, a 30-year fixed-rate term and otherwise identical loan characteristics.
| Scenario | Interest Rate | Monthly Principal and Interest |
|---|---|---|
| Borrower A | 6.25% | $1,970 |
| Borrower B | 6.75% | $2,076 |
| Difference | 0.50 percentage points | $106 |
These are hypothetical figures, not current Faster Mortgage rate quotes. Actual pricing depends on the loan program, credit profile, down payment, loan amount, occupancy, market conditions and other factors.
Over 30 years, that difference represents approximately $38,000 in additional scheduled principal and interest, assuming the rates remain fixed and payments are made as scheduled.
What Factors Do Mortgage Lenders Review Besides Credit Scores?
A strong credit score does not automatically guarantee mortgage approval. Lenders evaluate several financial factors together.
1. Payment History
Your payment history demonstrates how consistently you meet financial obligations.
Late payments, defaults, collections and other negative credit events may affect mortgage eligibility.
Recent serious delinquencies can be particularly important during underwriting.
2. Credit Utilization
Credit utilization measures how much of your available revolving credit you are using.
For example, if your credit card has a $10,000 limit and you carry a $7,000 balance, your utilization is 70%.
High utilization may negatively affect your credit score and indicate greater dependence on borrowed money.
Reducing revolving balances before applying may help strengthen your credit profile.
3. Debt-to-Income Ratio
DTI measures your monthly debt obligations against your gross monthly income.
Gross monthly income: $8,000
Total monthly debt obligations: $3,200
DTI ratio: 40%
A lower DTI ratio generally provides more room in your budget for mortgage payments.
However, acceptable DTI limits vary by loan program and underwriting findings.
4. Employment and Income Stability
Lenders review employment history, income consistency and the likelihood that income will continue.
Self-employed borrowers may need additional documentation, including tax returns, business financial statements or other supporting records.
5. Savings and Financial Reserves
Your savings can demonstrate your ability to cover the down payment, closing costs and unexpected expenses.
Certain mortgage programs may also require borrowers to maintain additional reserves after closing.
How to Improve Your Credit Score Before Applying for a Mortgage
Preparing your credit profile before submitting a mortgage application can help improve your borrowing options.
Here are practical steps to consider.
Review All Three Credit Reports
Check your credit reports from Equifax, Experian and TransUnion.
Look for:
- ✓ Incorrect personal information.
- ✓ Accounts you do not recognize.
- ✓ Incorrect payment records.
- ✓ Duplicate collections.
- ✓ Outdated negative information.
- ✓ Incorrect outstanding balances.
Dispute inaccurate information with the appropriate credit reporting agency.
Pay Bills on Time
Payment history is an important component of credit scoring.
Make all credit card, loan and other reported debt payments by their due dates. Consider automatic payments or reminders to avoid accidental late payments.
Reduce Credit Card Balances
Lowering revolving balances can improve your credit utilization.
Avoid relying on new credit cards to manage existing balances immediately before applying for a mortgage.
Avoid Unnecessary Credit Applications
Opening multiple accounts or applying for additional financing shortly before a mortgage application may affect your credit profile.
Avoid taking on unnecessary new debt during the mortgage preparation process.
Keep Older Accounts Open When Appropriate
The age and history of your credit accounts can contribute to your credit profile.
Avoid closing established accounts without understanding the potential impact on your credit utilization and overall credit history.
Allow Time for Credit Improvements to Appear
Credit reporting updates do not necessarily happen immediately.
If you pay down a balance or correct an error, allow time for the information to be updated and reflected in your credit profile.
Read our upcoming supporting guide: How to Improve Your Credit Score Before Applying for a Mortgage.
Can You Get a Mortgage in New Jersey With a Low or Limited Credit Score?
Yes, some borrowers with lower scores or limited traditional credit histories may still have mortgage options.
The available options depend on the loan program, lender requirements and overall financial profile.
FHA Financing
Eligible borrowers may qualify with scores below 580 if they meet the applicable down payment and underwriting requirements.
VA Financing
Eligible veterans may explore VA-backed financing because the VA itself does not establish a minimum credit score.
Alternative Credit Evaluation
Certain programs and underwriting methods may consider verified rental or utility payment histories when traditional credit information is insufficient.
Credit Preparation
Borrowers who do not currently meet lender requirements may benefit from reviewing their credit reports, reducing debt and addressing reporting errors before applying.
The NJHMFA also advises prospective borrowers not to assume they are automatically ineligible because of their credit history. Its guidance encourages individual evaluation and lender prequalification.
If your credit profile needs improvement, a mortgage professional can help identify realistic options and explain what steps may make you more prepared to apply.
How to Choose the Right Mortgage Based on Your Credit Profile
Selecting a mortgage requires balancing credit requirements, monthly payments, down payment, interest rate and long-term affordability.
Consider these factors before choosing a loan.
| Your Financial Situation | Mortgage Option to Explore |
|---|---|
| Limited savings and qualifying credit | FHA |
| Established credit and stable income | Conventional |
| Eligible veteran or service member | VA |
| Property in an eligible USDA area | USDA |
| Considering an initially lower adjustable rate | ARM |
| Financing a higher-value property | Jumbo |
| Eligible first-time New Jersey buyer | NJHMFA participating programs |
These are starting points for discussion, not automatic recommendations.
Step 1: Review Your Credit Profile
Understand your current scores, payment history, outstanding balances and any reporting issues.
Step 2: Calculate Your DTI Ratio
Review your monthly income and debt obligations to estimate how much mortgage payment you may comfortably support.
Step 3: Compare Mortgage Programs
Ask about FHA, conventional, ARM, jumbo and applicable assistance programs.
Step 4: Evaluate Your Down Payment and Savings
Consider your available funds, closing costs and any required reserves.
Step 5: Request a Mortgage Prequalification or Preapproval
A mortgage professional can review your financial information and help identify potential loan options.
Step 6: Compare the Complete Loan Terms
Review interest rates, mortgage insurance, fees, closing costs and monthly payments before making a decision.
Frequently Asked Questions About Credit Scores and Mortgages in New Jersey
Q. What is the minimum credit score needed for a mortgage in New Jersey?
There is no single minimum credit score for every mortgage in New Jersey. FHA guidelines allow eligible borrowers with scores of 580 or higher to qualify for maximum financing, while manually underwritten conventional loans may have different minimums. Lenders can also apply additional requirements.
Q. Can I buy a house in New Jersey with a 580 credit score?
Yes, it may be possible. FHA guidelines generally allow eligible borrowers with a 580 minimum decision credit score to qualify for maximum financing, subject to other requirements. Individual lenders may have stricter standards.
Q. Is a 620 credit score good enough to get a mortgage?
A 620 score may meet certain conventional and NJHMFA program requirements. However, approval also depends on income, DTI, down payment, credit history and underwriting findings.
Q. Can I qualify for an FHA loan with a 500 credit score?
FHA guidelines allow scores between 500 and 579 with a maximum 90% loan-to-value ratio, generally requiring at least 10% down for a standard purchase. Lender overlays and other eligibility requirements apply.
Q. Does a higher credit score help me get a lower mortgage rate?
Generally, yes. Stronger credit profiles may qualify for more competitive mortgage pricing. However, interest rates also depend on loan type, down payment, loan amount, market conditions and other risk factors.
Q. What credit score does NJHMFA require?
The NJHMFA First-Time Homebuyer Program requires a minimum representative credit score of 620 under its October 19, 2026 lender guide. Borrowers below 660 are subject to a maximum 45% DTI requirement under the program.
Q. Can I get a mortgage if I have no credit history?
Possibly. Certain underwriting programs may consider alternative credit references, such as verified rental or utility payments. Eligibility depends on the mortgage program and lender requirements.
Q. How long does it take to improve my credit score before applying?
The timeline varies depending on your credit history, outstanding balances, reporting errors and recent negative events. Some improvements may appear after the next reporting cycle, while rebuilding a damaged credit history can take considerably longer.
Q. Does applying for multiple mortgages hurt my credit score?
Mortgage credit inquiries made within a qualifying rate-shopping window are generally treated as a single inquiry for scoring purposes. The CFPB explains that the applicable shopping window can be 45 days. Avoid unnecessary applications for unrelated credit during the mortgage process.
Q. Can I refinance my mortgage with a lower credit score?
It may be possible, depending on the refinance program, lender requirements, equity, income and overall financial profile. Different refinance options have different eligibility criteria, so borrowers should compare available programs before proceeding.
Get Help Exploring Your Mortgage Options in New Jersey
Your credit score is an important part of the mortgage approval process, but it should not be the only factor guiding your home financing decision.
Whether you are purchasing your first home, exploring conventional or FHA financing, considering an ARM or jumbo mortgage, or evaluating refinance opportunities, understanding your financial position can help you make informed decisions.
At Faster Mortgage, we help New Jersey borrowers explore mortgage financing options based on their individual circumstances and homeownership goals.
You do not have to navigate credit requirements and mortgage guidelines alone.
Ready to Explore Your Mortgage Options?
Contact Faster Mortgage to discuss your credit profile, financing goals and potential loan programs.
Faster Mortgage
Phone: +1 609-431-5050
Website: www.fastermortgage.com
Office: 318 Chestnut St, Suite #2A, Roselle Park, NJ 07204
NMLS #2660033
Disclaimer: Mortgage eligibility, interest rates and loan terms are subject to lender approval, applicable underwriting requirements, property eligibility and program guidelines. Published minimum credit score requirements may change and individual lenders may impose additional restrictions. This article is for educational purposes and does not constitute a loan approval or commitment to lend.